Industry Case Study
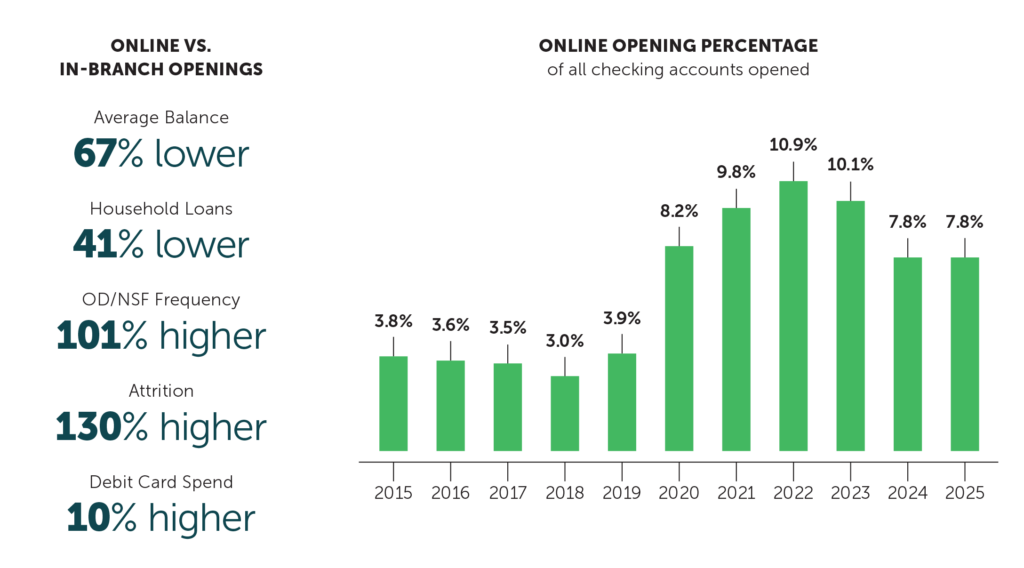
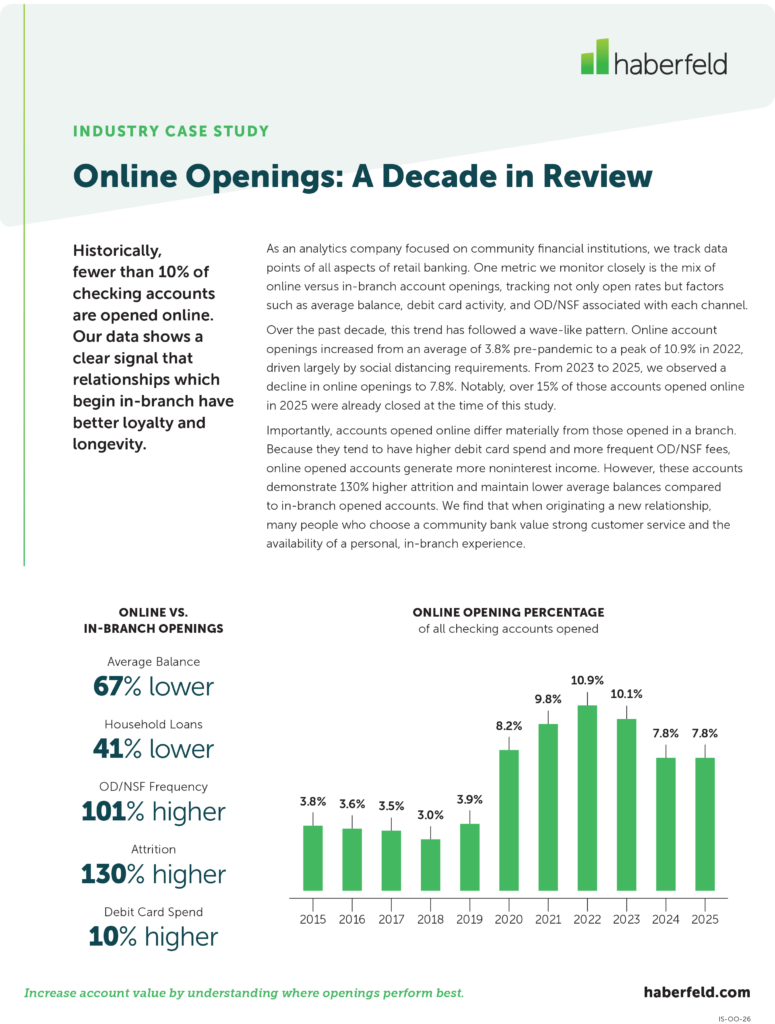
Historically, fewer than 10% of checking accounts are opened online. Our data shows a clear signal that relationships which begin in-branch have better loyalty and longevity.
As an analytics company focused on community financial institutions, we track data points of all aspects of retail banking. One metric we monitor closely is the mix of online versus in-branch account openings, tracking not only open rates but factors such as average balance, debit card activity, and OD/NSF associated with each channel.
Over the past decade, this trend has followed a wave-like pattern. Online account openings increased from an average of 3.8% pre-pandemic to a peak of 10.9% in 2022, driven largely by social distancing requirements. From 2023 to 2025, we observed a decline in online openings to 7.8%. Notably, over 15% of those accounts opened online in 2025 were already closed at the time of this study.
Importantly, accounts opened online differ materially from those opened in a branch. Because they tend to have higher debit card spend and more frequent OD/NSF fees, online opened accounts generate more noninterest income. However, these accounts demonstrate 130% higher attrition and maintain lower average balances compared to in-branch opened accounts. We find that when originating a new relationship, many people who choose a community bank value strong customer service and the availability of a personal, in-branch experience.